When you sit down to create an estate plan, writing a will is usually the first step. You might assume that once your will is signed, your wishes are locked in and your assets will be distributed exactly as you outlined. But there is a common estate planning mistake that can completely override your will: forgetting about beneficiary designations and account titling.
A will does not control every asset. In fact, some of your most valuable assets—like your retirement accounts and life insurance policies—are likely governed by separate beneficiary forms. If those forms contradict your will, the beneficiary forms almost always win. Understanding the difference between assets controlled by your will and assets that bypass it is crucial for ensuring your money goes where you want it to.
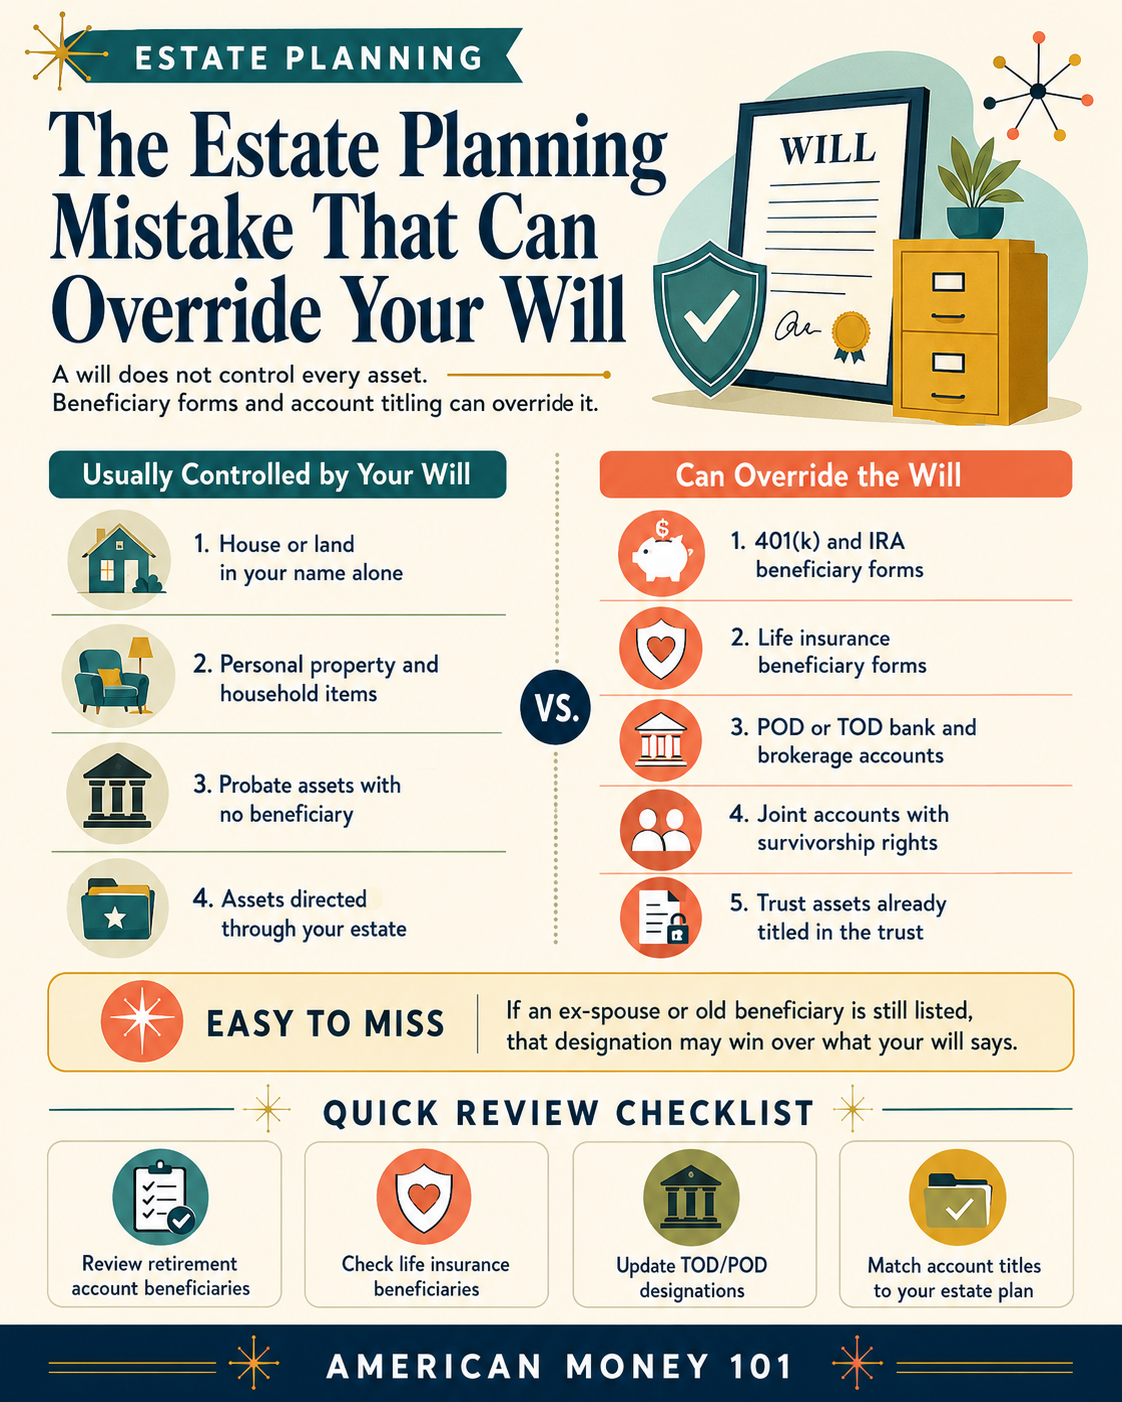
Assets Usually Controlled by Your Will
Assets that are distributed according to your will are known as "probate assets." These are typically items owned solely in your name without any attached beneficiary designation. When you pass away, these assets must go through the probate court process before they can be distributed to your heirs.
Common examples of assets controlled by your will include:
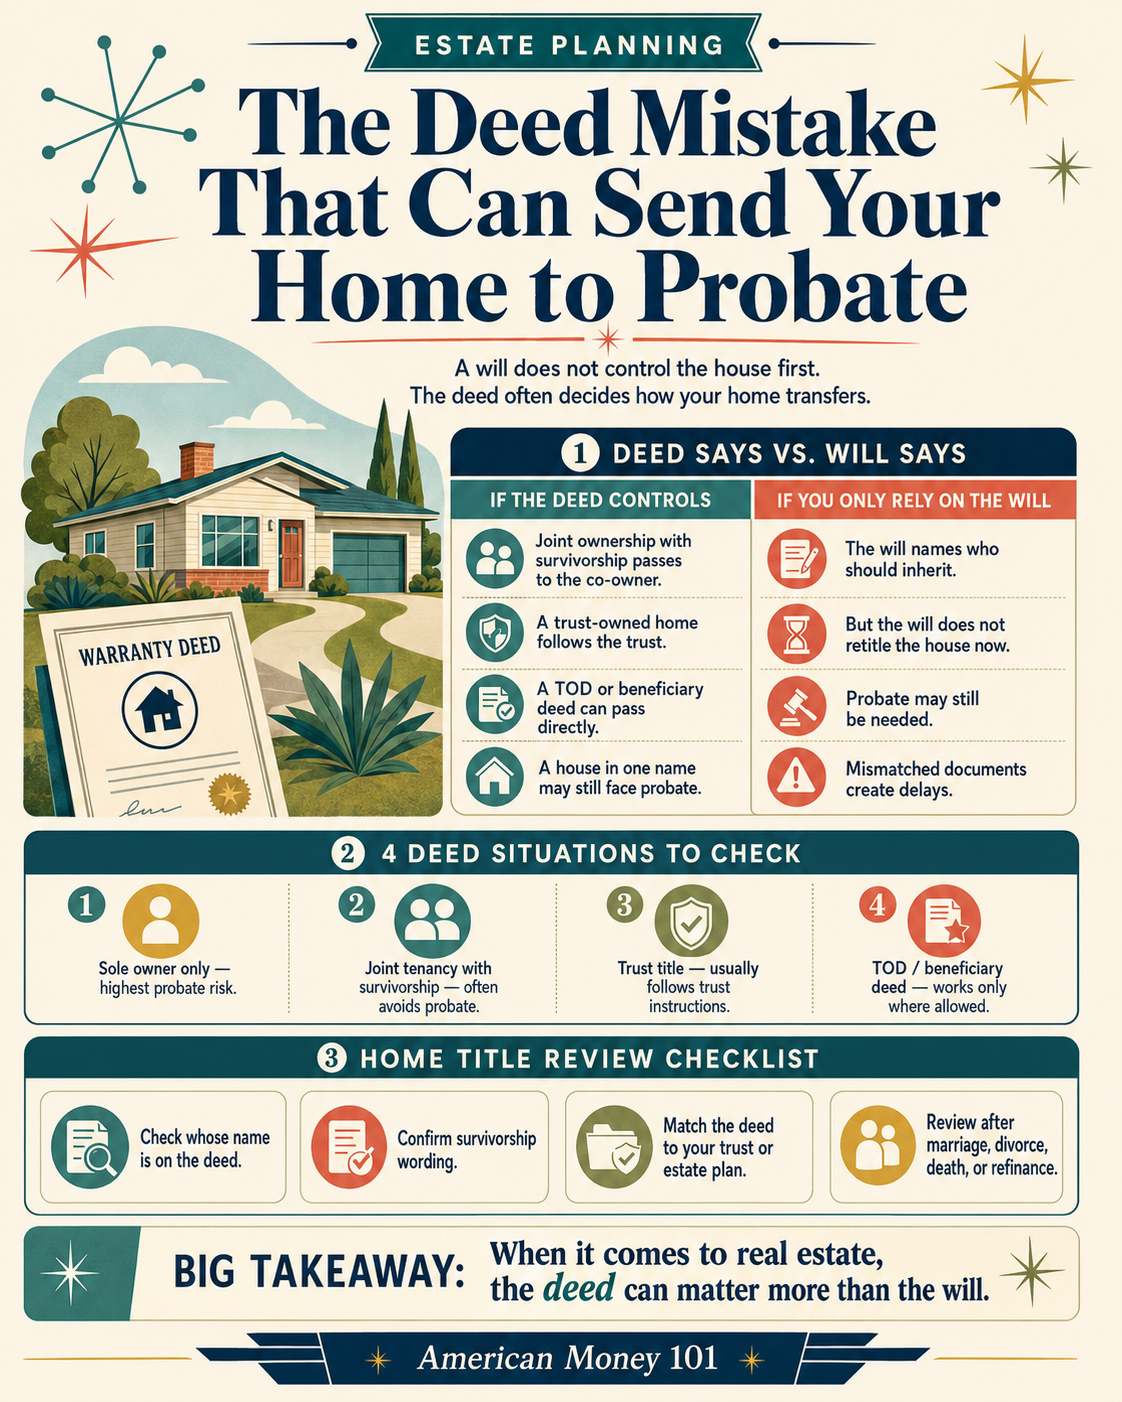
- House or land in your name alone: If you own real estate solely in your name, your will dictates who inherits it.
- Personal property and household items: Things like furniture, jewelry, art, and vehicles usually pass through your will.
- Probate assets with no beneficiary: Any bank account or investment account solely in your name that does not have a designated beneficiary will be controlled by your will.
- Assets directed through your estate: Sometimes, people intentionally name their estate as the beneficiary of an account, which means those funds will be distributed according to the will.
Assets That Can Override the Will
Assets that bypass the will and the probate process are called "non-probate assets." These assets transfer directly to the surviving joint owner or the designated beneficiary, regardless of what your will says. This is where many estate planning mistakes happen.
Here are the primary types of assets that can override your will:
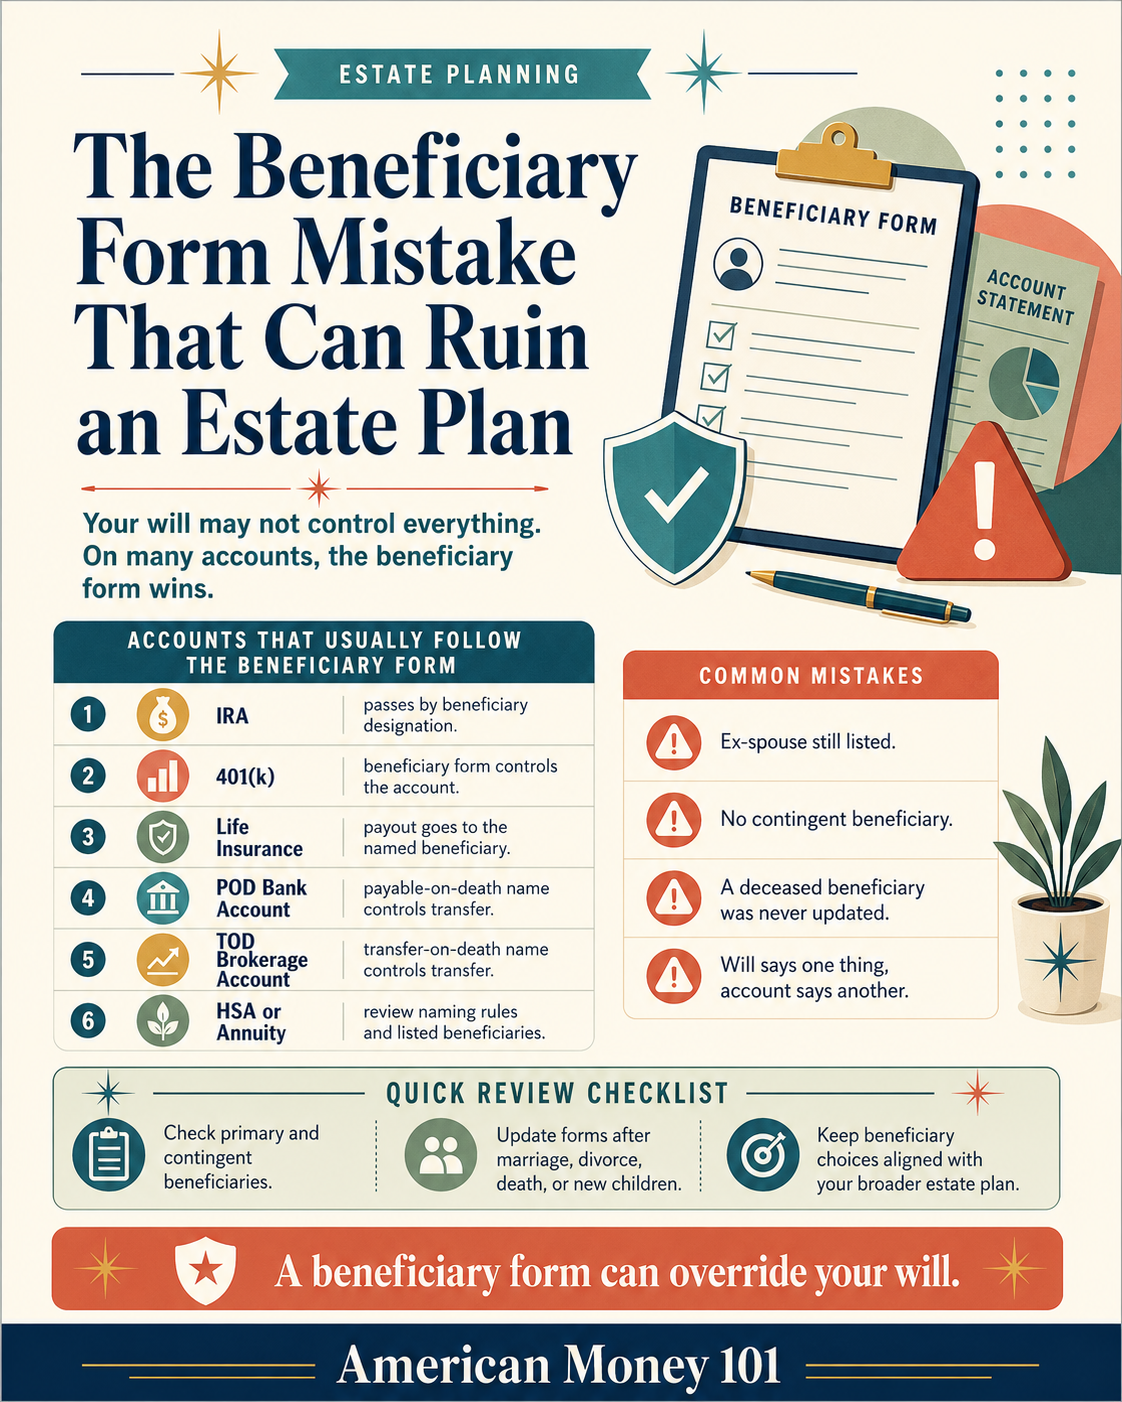
- 401(k) and IRA beneficiary forms: Retirement accounts require you to name a beneficiary when you open them. The person listed on that form will inherit the account.
- Life insurance beneficiary forms: The death benefit from a life insurance policy pays out directly to the named beneficiaries.
- POD or TOD bank and brokerage accounts: You can add a Payable on Death (POD) or Transfer on Death (TOD) designation to bank and brokerage accounts, allowing them to pass directly to the named person.
- Joint accounts with survivorship rights: If you own a bank account or real estate jointly with someone else (like a spouse) with "rights of survivorship," the surviving owner automatically takes full ownership.
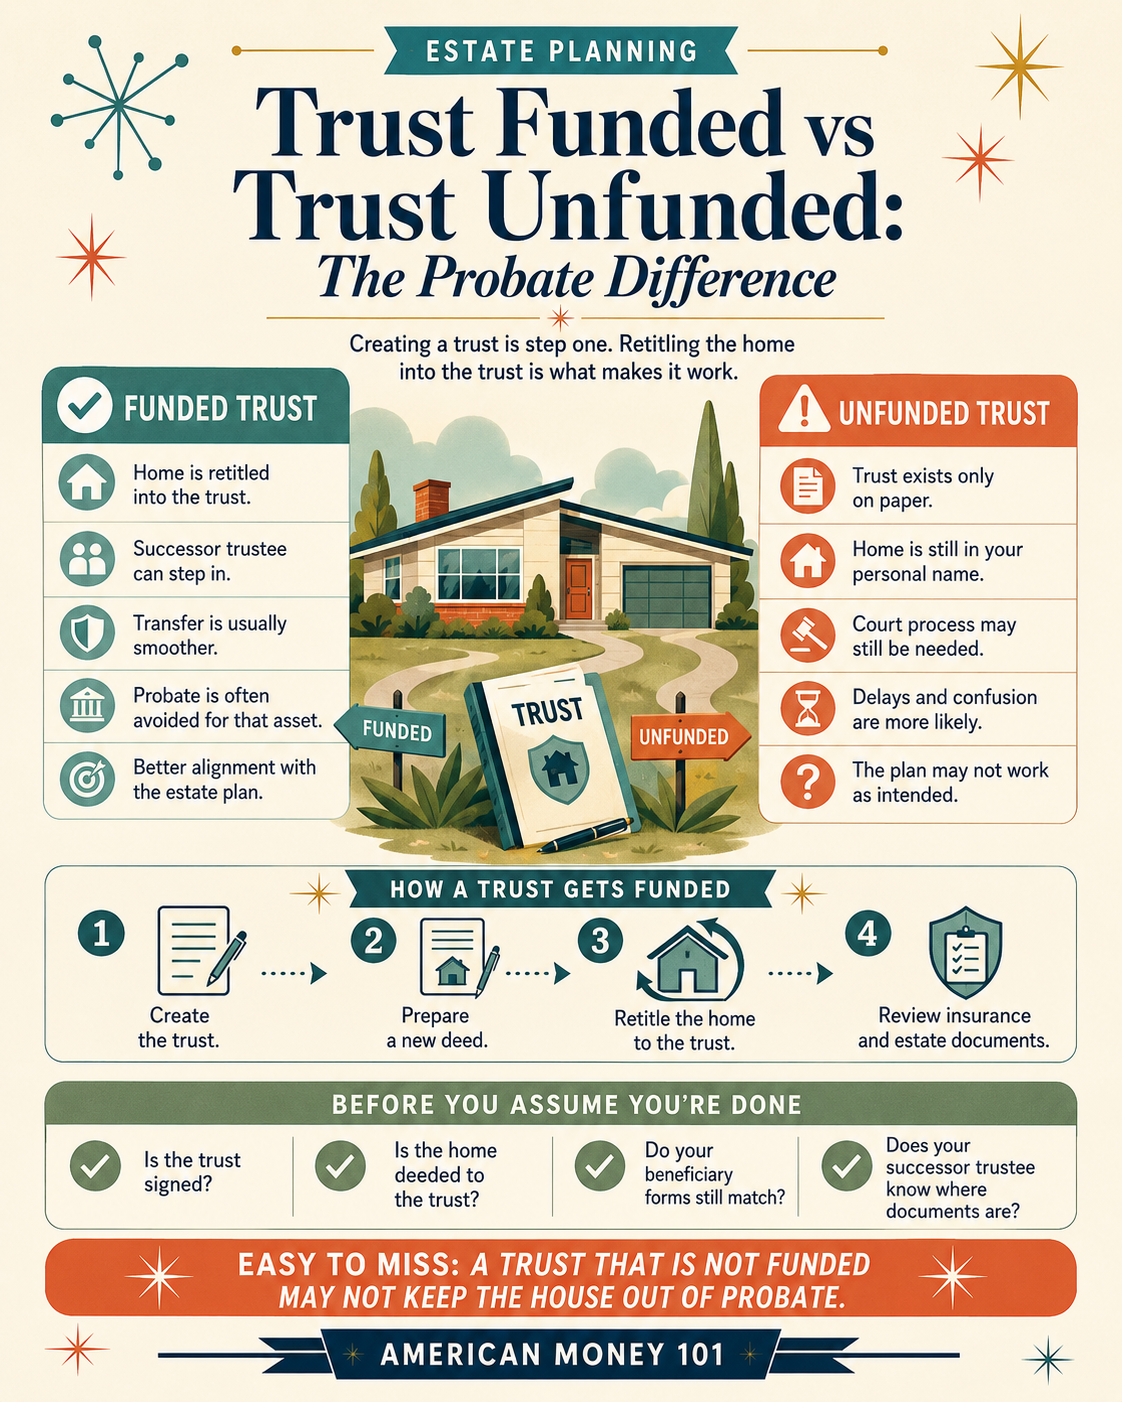
- Trust assets already titled in the trust: Assets that have been properly transferred into a living trust are governed by the trust document, not your will.
The Danger of Outdated Beneficiaries
Because beneficiary designations override your will, keeping them updated is incredibly important. It is easy to miss this step when your life circumstances change. For example, if you named your spouse as the beneficiary of your 401(k) when you first started your job, but you later divorced and remarried, your ex-spouse might still be listed on the form.
If you pass away and your ex-spouse is still the designated beneficiary on your retirement account or life insurance policy, they will likely inherit that money—even if your recently updated will explicitly states that you want everything to go to your new spouse or your children. The financial institution managing the account is legally bound to follow the beneficiary form on file.
Quick Review Checklist
To ensure your estate plan actually works the way you intend, you need to coordinate your will with your beneficiary designations and account titles. Make it a habit to review these details every few years, or after any major life event like a marriage, divorce, birth of a child, or the death of a loved one.
- Review retirement account beneficiaries: Log in to your 401(k), IRA, and pension accounts to verify who is listed as the primary and contingent beneficiaries.
- Check life insurance beneficiaries: Contact your life insurance provider to confirm your current beneficiary designations.
- Update TOD/POD designations: Check with your bank and brokerage firms to see if you have POD or TOD designations on your accounts, and update them if necessary.
- Match account titles to your estate plan: Ensure that the way your assets are titled (e.g., joint ownership, individual ownership, or in a trust) aligns with your overall goals.
Taking a few minutes to review these forms can prevent major headaches and ensure your assets are distributed exactly as you wish.