You have finally done it. You sat down, made the hard decisions, and drafted a will to ensure your assets go exactly where you want them to after you are gone. You might think your estate plan is rock solid, but there is a hidden trap that catches many people off guard: the beneficiary form. The truth is, your will may not control everything. On many of your most valuable accounts, the beneficiary form wins.
When you open a retirement account or buy a life insurance policy, you are usually asked to name a beneficiary. What many people do not realize is that this simple form acts as a legally binding contract. If the instructions on that form conflict with your will, the form almost always takes precedence. Understanding how these forms work and keeping them updated is crucial to ensuring your money actually goes to the people you intend.
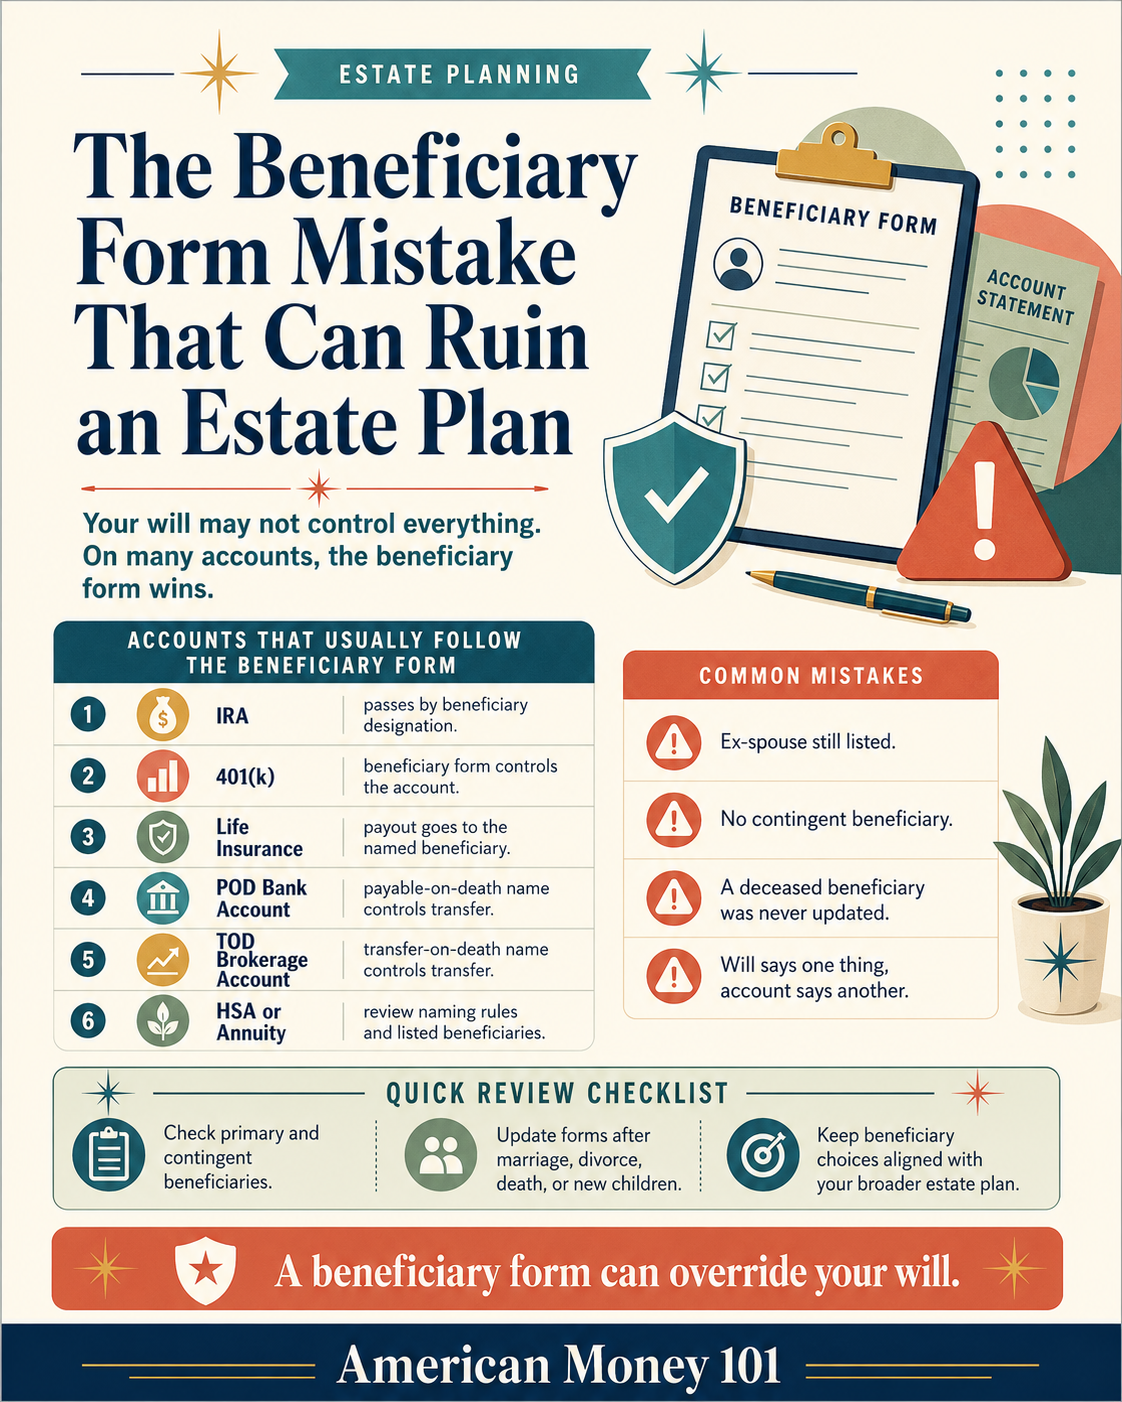
Accounts That Usually Follow the Beneficiary Form
Not all of your assets pass through your will. Many financial accounts are designed to transfer directly to a named beneficiary, bypassing the lengthy and often public probate process. Here are the common types of accounts where the beneficiary form controls the payout:
- IRA: Individual Retirement Accounts pass by beneficiary designation.
- 401(k): The beneficiary form controls who inherits the funds in your employer-sponsored retirement account.
- Life Insurance: The death benefit payout goes directly to the named beneficiary on the policy.
- POD Bank Account: A Payable-On-Death (POD) designation controls the transfer of funds in checking or savings accounts.
- TOD Brokerage Account: A Transfer-On-Death (TOD) designation controls the transfer of investments in a taxable brokerage account.
- HSA or Annuity: Health Savings Accounts and annuities also have specific naming rules and listed beneficiaries that dictate who receives the remaining funds.
Common Beneficiary Mistakes to Avoid
Because beneficiary forms are often filled out quickly when an account is first opened, they are easily forgotten. This "set it and forget it" mentality leads to several common, and potentially disastrous, mistakes:
- Ex-spouse still listed: If you divorce but forget to remove your ex-spouse from your 401(k) or life insurance policy, they could legally inherit that money, regardless of what your divorce decree or updated will says.
- No contingent beneficiary: A primary beneficiary is your first choice to receive the asset. A contingent (or secondary) beneficiary is the backup in case the primary beneficiary dies before you do. Failing to name a backup can force the asset into probate.
- A deceased beneficiary was never updated: If your named beneficiary passes away and you do not update the form, the asset may end up going to your estate, subjecting it to probate and potentially different heirs than you intended.
- Will says one thing, account says another: This is the classic conflict. If your will leaves everything to your current spouse, but your IRA still names your sibling from when you opened it 20 years ago, your sibling gets the IRA.
The Danger of Naming Minors
While it is natural to want to leave money to your children or grandchildren, naming a minor directly on a beneficiary form can create significant legal hurdles. Minors cannot legally own or manage large sums of money. If a minor inherits an account directly, a court will typically have to appoint a guardian to manage the funds until the child reaches the age of majority (usually 18 or 21, depending on the state). This process can be expensive, time-consuming, and intrusive. Instead, many people choose to set up a trust for the minor and name the trust as the beneficiary, allowing a trustee of their choosing to manage the money according to their specific instructions.
Quick Review Checklist for Your Beneficiary Forms
Keeping your beneficiary designations accurate does not have to be a massive undertaking, but it does require periodic attention. Use this quick checklist to ensure your forms are in order:
- Check primary and contingent beneficiaries: Verify who is currently listed on every account and ensure you have backups named.
- Update forms after major life events: Make it a habit to review your forms after a marriage, divorce, death of a loved one, or the birth or adoption of new children.
- Keep beneficiary choices aligned with your broader estate plan: Ensure the people named on your forms match the overall intentions outlined in your will or trust.
Remember, a beneficiary form can override your will. Taking a few minutes to review and update these forms can save your loved ones from unnecessary stress, legal battles, and financial heartache during an already difficult time.